Every investor wants to keep more of what they earn as tax efficiency becomes a bigger talking point in the UK this year. Recent changes to ISA rules and dividend tax rates have prompted many people to think more carefully about how their money is taxed. While tax planning matters considerably, it works best when it is aligned with investment goals and risk appetite.
Tax should be an important consideration of any investment strategy
Tax still shapes what an investor actually keeps at the end of the day, and this year has brought changes worth knowing about. The Autumn Budget 2025 confirmed that the Cash ISA allowance will be cut to £12,000 per tax year from 2027, though the overall ISA limit holds steady, since the remaining £8,000 of the £20,000 allowance will need to go into investment-based accounts such as Stocks and Shares ISAs. Capital gains tax allowances have shrunk too, now sitting at just £3,000, which means profits held outside a tax wrapper get taxed sooner than they used to. There is also a planned rise in the tax on savings income, with the basic rate set to increase from 20% to 22%, underscoring why the tax side of investing needs regular attention.
Announcing the changes, Chancellor Rachel Reeves said she would "reform our Isa system, keeping the full £20,000 allowance while designating £8,000 of it exclusively for investment." In short, savers keep the same total pot, but part of it now has to work harder than sitting in cash. Aegon's pensions director Steven Cameron said "time will tell if this blunt intervention will deliver on its intended purpose," pointing out that a lower cash limit alone may not be enough to turn cautious savers into investors.
The Starting Point: Investment goals
Before tax comes into the picture, an investor needs to know what the money is for, as this determines the primary approach. Someone saving for a house deposit in three years will have very different needs from an investor building a UK retirement pot over the next 20 years. The goal, the amount of time available and the level of risk an investor can comfortably take should help shape the portfolio. A generous tax benefit does little to help if the investment itself is too risky, difficult to access when the money is needed or simply unsuitable for the investor’s objective. This is why taxes should usually come later in the planning process. Once the destination and acceptable level of risk are clear, advisers can then look at the investments most likely to get the client there and how those investments can be held more tax-efficiently. The timeline attached to a goal usually decides how much risk makes sense, since a shorter goal calls for steadier choices while a longer one can absorb more ups and downs. A rough guide to how goals typically map to timeframes looks like this:
Time frame | Typical goals | Risk approach |
|---|---|---|
Short term (1 to 3 years) | Emergency fund, holiday, a car | Low risk, easy access |
Medium term (3 to 10 years) | House deposit, further study | Moderate risk, some growth |
Long term (10 years plus) | Retirement, legacy planning | Higher risk, more growth focus |
The Right Asset Mix
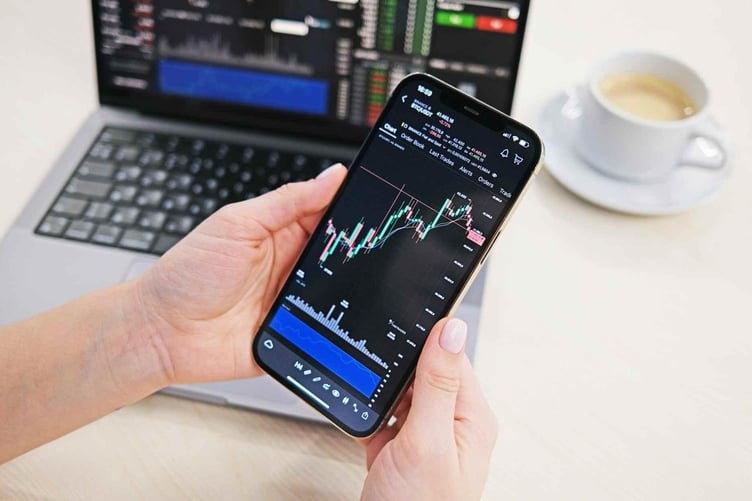
Once the goal and risk level are clear, the next question is how to spread the money across different types of investments. This is asset allocation, and study after study has shown it drives more of an investor's long term return than picking individual stocks or timing the market ever does. A mix might include shares for growth, bonds for steady income, cash for short term needs and alternatives like property or commodities for diversification. More speculative activities also need to be considered separately. CFD trading with Oanda, for example, allows traders to speculate on price movements without owning the underlying asset and usually involves leverage. Here is a broader breakdown of how these pieces typically function:
Asset type | Role in portfolio | Typical volatility | Best suited for |
|---|---|---|---|
Cash and equivalents | Liquidity, capital protection | Very low | Emergency funds, goal under 3 years |
Government and corporate bonds | Steady income, cushions against swings | Low to moderate | Medium term goals, income focus |
UK and global shares | Long term capital growth | High | Long horizons, higher risk tolerance |
Property and REITs | Diversification, inflation hedge | Moderate to high | Balancing a stock heavy portfolio |
Commodities and gold | Hedge against inflation and market shock | High | Small allocation for diversification |
A common rule of thumb, sometimes called the "110 minus your age" guide, suggests holding that percentage in shares and the rest in bonds and cash, though it is a starting point rather than a fixed formula. In practice, this tends to translate into a few broad profiles:
Investor profile | Typical mix | Who it suits |
|---|---|---|
Conservative | 20% shares, 60% bonds, 20% cash | Near or in retirement, short time horizon |
Balanced | 50% shares, 40% bonds, 10% cash | Medium term goals, moderate risk tolerance |
Growth focused | 80% shares, 15% bonds, 5% cash | Long time horizon, higher risk tolerance |
These figures are only a starting point. An investor's actual mix should reflect their specific goals, income needs and how they personally react to market swings, which is why many people choose to review their allocation with a financial adviser rather than rely on a template alone.
Make the Asset Mix Tax Efficient
Tax efficiency will always matter to UK investors, especially with allowances shrinking and rates on the rise. With the goals, risk level and asset mix settled, the final step is deciding where each investment should sit to keep as much of the return as possible. ISAs remain the simplest tool for this in the UK, since all growth and income inside one stays free from income tax and capital gains tax, and the full £20,000 allowance resets every tax year. Pensions work alongside ISAs, offering tax relief on contributions plus tax free growth, which makes them especially useful for long term goals like retirement.
Comments
This article has no comments yet. Be the first to leave a comment.